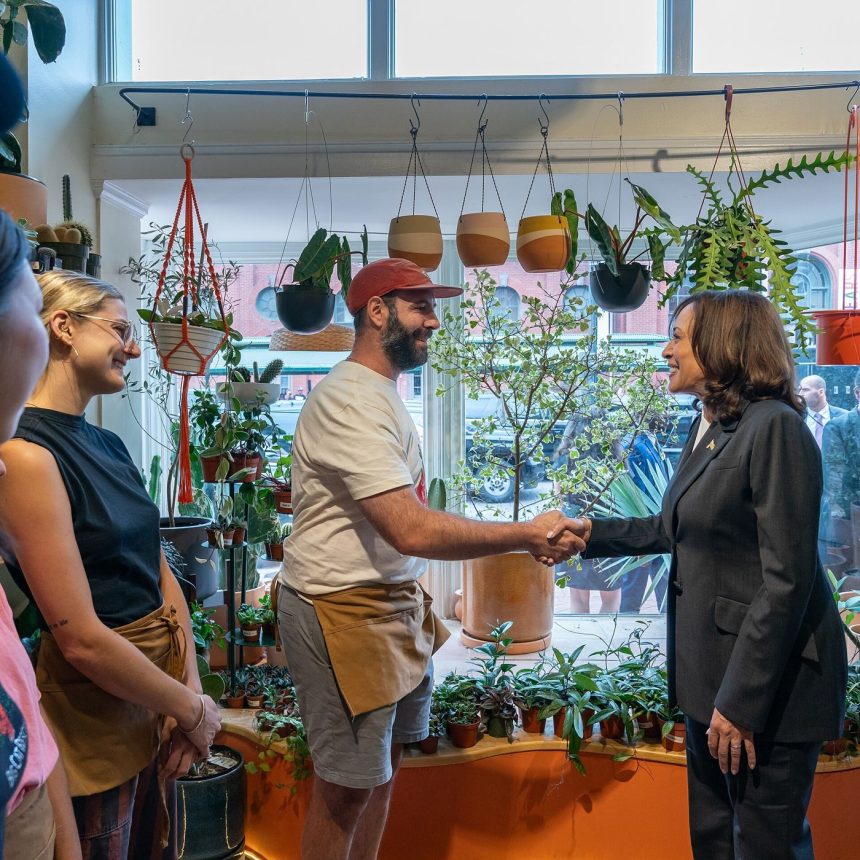
Small business lending is recovering after several tight years, with banks and specialist lenders competing for creditworthy firms again. Approval rates have climbed, and loan pricing has eased for businesses with solid records, according to industry surveys and lender reports.
Why It Matters Now
small business lending is being watched closely by households as well as investors, because decisions taken in boardrooms quickly reach monthly budgets. Lenders, savers and pension funds all react to the same signals, yet they feel the effects at different speeds. Economists advise looking beyond a single headline figure: wages, borrowing costs, confidence and trade all interact, and a change that helps one group can squeeze another, at least until markets and employers have time to adjust.
Owners are using the funds mainly for equipment, premises and working capital rather than expansion gambles. Advisers recommend comparing total costs, not headline rates, and keeping cash reserves intact, because lenders still tighten quickly when economic data disappoints or defaults begin rising in a sector.
What Experts Are Watching
For small business lending, the data tell a more nuanced story than the headlines suggest. Analysts compare current figures with long term averages, adjust for seasonal patterns and check whether the trend is broad or driven by a few large players. That discipline matters for ordinary decisions too. Whether someone is fixing a mortgage, pricing a product or planning a hire, understanding the direction of travel is usually more useful than reacting to one dramatic day of market movement.
Several questions remain open, and honest reporting should say so. Timelines may slip, costs may rise and early results may not generalise to every place or person. That uncertainty is not a reason to ignore the story; it is a reason to follow reliable sources and update conclusions as evidence arrives. The strongest coverage will keep explaining what is known, what is estimated and what nobody yet knows, so readers can make decisions without false confidence or unnecessary alarm.
Context also matters historically. Similar shifts in earlier decades followed a recognisable pattern: early excitement, a period of disappointment as costs and limits became clear, then steady improvement as standards, training and infrastructure caught up. Remembering that pattern helps readers judge today’s claims proportionately. It neither guarantees success nor predicts failure, but it does suggest that patient, well funded work tends to outlast both hype and cynicism, and that the most durable benefits often appear in ordinary places rather than launch events.
There is also a human side that statistics can miss. Behind every figure are people adjusting routines, retraining, moving money or changing plans in response to new information. Their experience is a useful test of whether a trend is real: when change reaches kitchens, clinics, classrooms and workshops, it has usually passed beyond speculation. Listening to those voices, alongside official data, gives a fuller and fairer picture of what is actually happening and who is being helped or left behind.
Readers can follow our finance coverage for further updates on this story, and compare the details with reporting from the World Bank. As small business lending continues to develop, we will update this article with verified figures, named sources and reaction from the people most affected, so the record stays clear, accurate and useful for everyone following it closely.