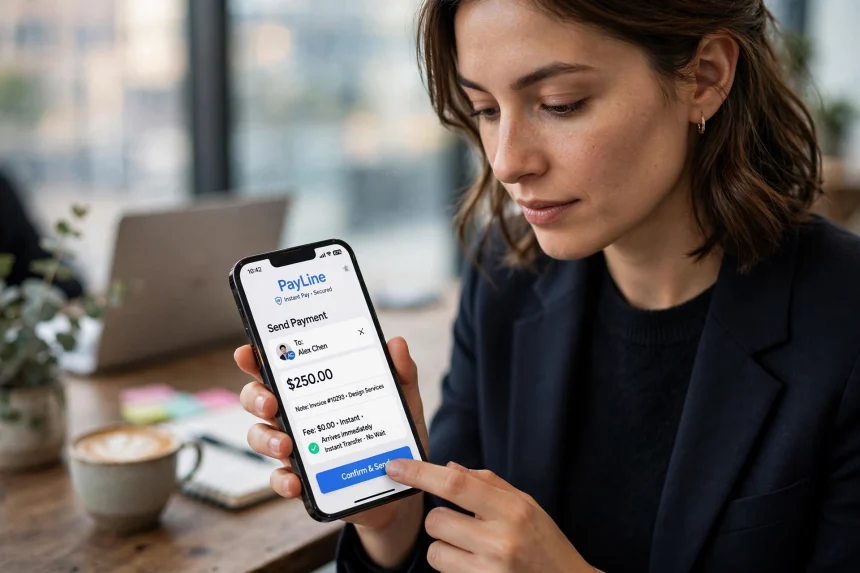
For most of modern banking history, moving money was strangely slower than moving information. A message could cross the world in a second, while a payment took days to clear. That gap is finally closing. Instant payment systems now allow funds to arrive, settle and become usable within seconds, at any hour, on any day of the year, and the change is quietly reshaping how businesses and households manage cash.
In the United States, two major networks lead the shift. The Federal Reserve operates FedNow, described in its overview of the FedNow Service as a system that lets banks offer instant payments around the clock. The private sector’s RTP network, run by The Clearing House, has offered real-time settlement since 2017. Together they are pushing instant settlement from a premium feature toward a basic expectation.
Why Speed Changes Cash Flow
For a small business, the difference between being paid today and being paid in three days is not cosmetic. It determines whether wages go out on time, whether a supplier can be paid before a discount expires and how much short-term borrowing a firm needs. Faster settlement reduces the float that once forced businesses to keep larger cash buffers or pay for bridging finance.
That is one reason bookkeeping and payment timing have become strategic topics for owners, as covered in our guide to the signs a business needs a professional bookkeeper. When money moves instantly, records, reconciliation and fraud checks have to keep up at the same speed.
Payroll, Bills and Everyday Life
Workers are among the clearest beneficiaries. Earned-wage access and instant payroll options let employees receive money they have already earned without waiting for a fixed payday or turning to expensive short-term credit. For households living close to their budget limits, receiving funds seconds after a shift ends can be the difference between paying a bill on time and incurring a late fee.
Billers benefit too. Utilities, insurers and landlords increasingly prefer instant payments because they confirm immediately, reducing failed-payment follow-ups and customer service disputes. Consumers, meanwhile, gain certainty: a payment sent is a payment received, with confirmation both sides can see.
Banks Face a New Competitive Test
Instant payments are not simply a technology upgrade for banks. They change the economics of deposits and the expectations customers bring to every transaction. Once a customer has experienced money arriving in seconds, a two-day delay feels like a defect, not a tradition. Community banks and credit unions therefore face pressure to connect to instant networks even though integration, staffing for round-the-clock operations and real-time fraud monitoring all cost money.
Fraud is the sharpest challenge. A payment that settles in seconds and cannot easily be reversed demands stronger checks before it is sent, not after. Banks are investing in behavioural analytics, confirmation-of-payee checks and customer warnings, while regulators stress that speed must not come at the expense of consumer protection.
A Global Race Already Under Way
The United States is, in this area, catching up rather than leading. India’s UPI, Brazil’s Pix and Europe’s instant SEPA systems already process enormous volumes in real time, often at little or no cost to users. Their success shows what happens when instant payment becomes national infrastructure: new services appear on top of it, from street-vendor QR payments to instant tax refunds.
American adoption is accelerating as more banks join the networks and as large employers, marketplaces and gig platforms build instant payout into their products. Consumer spending patterns, including the resilience described in our report on retailers beginning holiday hiring early, increasingly run through digital channels where customers expect settlement to be immediate.
What Happens Next
The next contest is interoperability: making sure a payment can move instantly between different banks, apps and eventually across borders. Cross-border instant payments remain slow and expensive today, and solving that problem is a major focus for central banks and payment firms alike.
Money that moves like a message will change habits in ways that are easy to underestimate. Businesses will plan around real-time balances, workers will expect real-time pay, and banks will compete on the quality of an experience measured in seconds. The cheque took centuries to fade. The waiting period for a domestic payment may disappear far faster.